Automated valuation tools are a fine place to start a conversation and a terrible place to end one. They work from public records and broad averages. They have never walked through your house, and in a county as varied as this one, that is a significant handicap.
Here's what actually sets the number.
1. Micro-location, not ZIP code
San Diego prices change block by block. A canyon view, a cul-de-sac, a corner lot on a busy street, a flight path, school attendance boundaries - these routinely move value by double digit percentages inside the same ZIP code. An algorithm averages them away.
2. Condition and the age of the big-ticket systems
Roof, HVAC, electrical panel, plumbing, windows and foundation. Two identical floor plans where one has a five-year-old roof and re-piped supply lines and the other doesn't are not the same asset. This is where my construction and rehabilitation background earns its keep: I can tell you what a buyer's inspector is going to find and what it will cost you in negotiation.
3. Permitted versus unpermitted square footage
That converted garage, added bedroom or enclosed patio may add real utility, but if it isn't permitted it usually isn't counted by an appraiser - and it can complicate a buyer's financing. Knowing this in advance changes how we market the home and how we price it.
4. Layout and flow
Two homes can show the same square footage and feel completely different. Bedroom count and placement, whether the primary suite is on the ground floor, whether the kitchen opens to the living space, and how the home connects to outdoor space all carry weight with San Diego buyers - often more weight than raw size.
5. Real, recent, comparable sales
A useful comparable is a similar home, in a similar location, that actually closed in the last 90 days. In a shifting market, six-month-old data is history, not evidence. I also read the sales that didn't close and the ones that closed with big credits - those tell you where the ceiling really is.
6. Today's buyer pool and financing
Price isn't only about your home. It's about what the buyers who want your home can borrow this month. Rate movement changes the size of the qualified buyer pool at each price band, and that determines whether you get one offer or five.
7. Carrying cost and timing
The highest list price is not always the highest net. Every month on market costs you mortgage interest, taxes, insurance and maintenance - and a stale listing invites lower offers. The right number is the one that gets you the most money in your pocket, at a date that works for your life.
How I build a real valuation
I walk the property, photograph the systems and finishes, pull closed and active comparables with adjustments I can show you line by line, model two or three pricing strategies with the likely net proceeds for each, and then we decide together. It takes about an hour of your time, there is no cost, and you are under no obligation to list.
If you'd like to know what your home would bring in today's market - whether you're selling this spring or just planning ahead - get in touch and we'll set it up.
FROM OUR BLOG
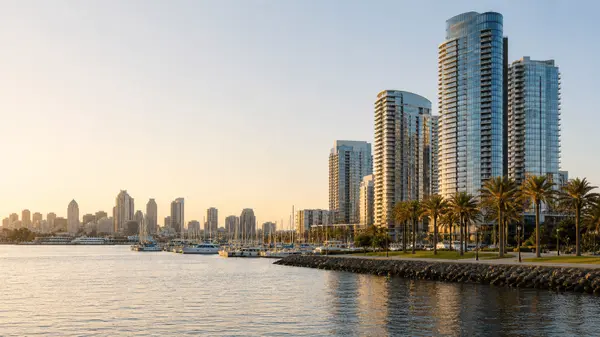
Downtown San Diego Condo Buyer's Guide: Little Italy, East Village, Marina and Gaslamp
Downtown San Diego isn't one market - it's half a dozen small ones stacked inside a few square miles. Two buildings three blocks apart can differ by hundreds of dollars a month in HOA dues and by a whole lifestyle. Here's how I help buyers tell them apart.Little ItalyThe most walkable neighborhood d
Getting Your San Diego Home Ready to List: A Pre-Market Checklist
Most of the money you make on a sale is decided before the first showing. In San Diego's market, buyers move quickly and compare your home against everything else that came on that week - so the goal of pre-market prep is simple: remove every reason for someone to hesitate.Here is the checklist I wa